Indonesia’s Central Bank and Treasury Lock In a Joint Calendar for State-Fund Flows
Kabarsaji.com – For the first time, Bank Indonesia and the Indonesian government have formalized a shared timetable governing when state-owned funds are deposited into and pulled out of state-owned banks. The move, announced by Deputy Governor Destry Damayanti, signals a shift from ad hoc treasury operations toward a predictable, coordinated rhythm of liquidity injections and withdrawals within the domestic banking system.
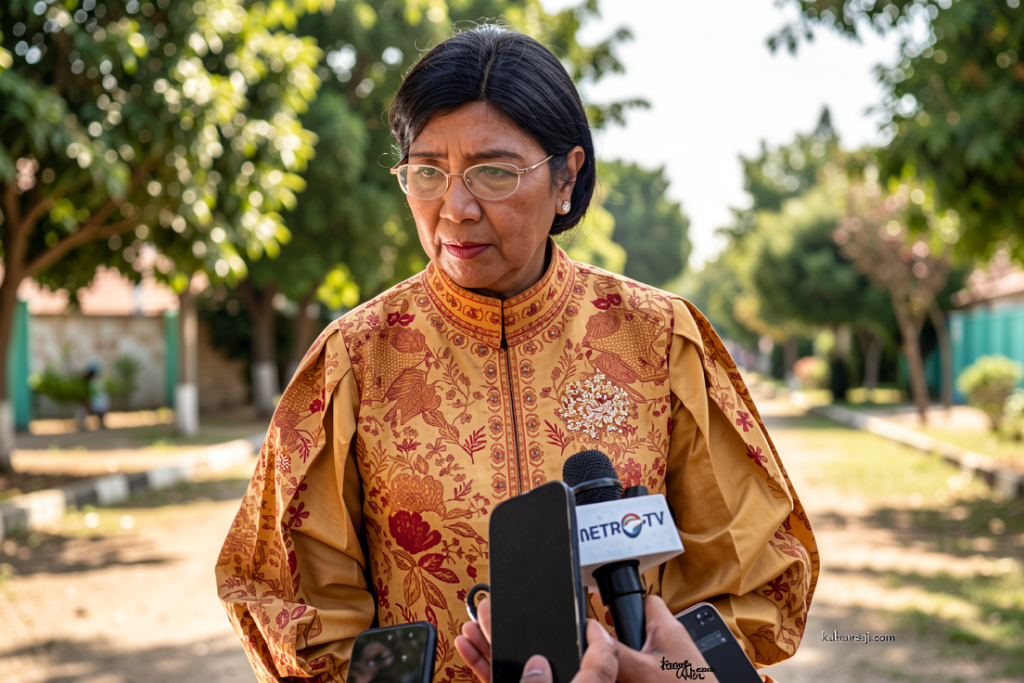
The announcement came on Thursday, September 3, 2026, during a panel at the 100 Indonesian Economists forum held in the Kempinski Grand Ballroom in Jakarta. Speaking to reporters after the session, Damayanti confirmed that the two institutions have moved beyond informal consultations and now operate under an agreed schedule for the placement and retrieval of government balances held at state-owned lenders.
“Future coordination regarding when funds are placed in state-owned banks and when the government will withdraw them has been discussed. There is now a timetable for it.”
Why a Fixed Schedule Matters
State-owned banks in Indonesia — including Bank Rakyat Indonesia, Bank Mandiri, Bank Negara Indonesia, and Bank Tabungan Negara — routinely hold large government deposits. The timing of those deposits and their subsequent withdrawal can create sudden surges or drains of liquidity in the interbank market. When the treasury parks a substantial sum overnight or for a short period, banks gain excess reserves; when that sum is recalled, the same banks face an abrupt contraction. Without a predictable calendar, commercial banks struggle to price short-term funding, and the central bank must intervene more frequently to smooth out volatility.
By codifying the schedule, Bank Indonesia gains advance visibility into upcoming liquidity shocks. It can pre-position repo facilities, adjust the standing repo rate, or calibrate foreign-exchange swap lines before a large withdrawal hits the system. The government, in turn, benefits from knowing exactly when its balances will be available for fiscal operations such as debt servicing or budget disbursement.
Shared Responsibility for Liquidity Management
Damayanti was explicit that the task of keeping adequate liquidity circulating in the financial system does not rest on the central bank alone. The treasury’s own cash-management decisions — how much to hold, where to park it, and when to move it — are equally consequential. She framed the arrangement as a matter of institutional synergy rather than unilateral central-bank action.
“So, once again, this comes down to synergy, because managing liquidity is not just BI’s task, but the government’s as well.”
The remark underscores a broader structural point: in economies where the state is a major participant in banking — as it is in Indonesia, through both ownership of lenders and the scale of its fiscal flows — the boundary between monetary policy and fiscal cash management is inherently porous. A timetable formalizes what was previously a series of bilateral phone calls and last-minute notifications.
Repo and FX-Swap Balances Approach Rp930 Trillion
Separately, Damayanti disclosed that Bank Indonesia’s standing liquidity-support instruments — primarily repo facilities and foreign-exchange swaps through which inbound foreign capital is converted into rupiah — have collectively reached a value in the range of Rp920 trillion to Rp930 trillion. The figure represents the gross stock of liquidity that the central bank has made available to the banking system through these channels.
“If we look at repo facilities, including FX swaps, where foreign capital enters and is converted into rupiah, it has reached around Rp920 trillion to Rp930 trillion, meaning liquidity is returning to the system.”
The scale of that number is worth contextualizing. At prevailing exchange rates, the figure corresponds to roughly US$55–57 billion of liquidity support outstanding. For a banking system whose total domestic deposits exceed Rp1,000 trillion, the repo-and-swap stock constitutes a meaningful share of short-term funding. Its growth, as Damayanti noted, indicates that liquidity conditions are normalizing after earlier periods of tighter funding.
Implications for Market Participants
For commercial banks, the published timetable reduces uncertainty in their daily funding planning. Treasury desks at state-owned lenders can now model expected inflows and outflows with greater precision, lowering the premium they charge on short-term interbank placements. For foreign investors holding rupiah-denominated assets, the FX-swap component of the liquidity package provides a transparent channel to convert dollar inflows into rupiah without bearing full spot-exchange risk.
For policymakers, the arrangement reduces the frequency with which Bank Indonesia must conduct open-market operations on an emergency basis. Fewer surprise liquidity events mean a smoother path for the policy rate and less distortion in short-term money-market rates.
Broader Context
Indonesia’s central bank has long managed a complex mandate that includes price stability, financial-system stability, and the smooth functioning of payment systems. In recent years, the scale of government fiscal flows — driven by infrastructure spending, sovereign-debt management, and pandemic-era stimulus — has amplified the liquidity-management challenge. The formalization of a joint timetable represents an institutional maturation: both sides accept that fiscal cash management and monetary liquidity management are two halves of the same operational problem, and that solving it requires a shared calendar rather than reactive firefighting.
The September 3 forum, which gathered roughly a hundred economists, policymakers, and academics in Jakarta, provided the public stage for the announcement. The timing — ahead of the final quarter of fiscal year 2026, when government spending typically accelerates — suggests the schedule is designed to absorb the seasonal liquidity surge associated with year-end budget execution.
Related Reading
Frequently Asked Questions
What is Bank Indonesia Govt Set Timeline for Fund?
Bank Indonesia Govt Set Timeline for Fund is the main topic of this guide. The article explains the context, practical details, and next steps readers should understand.
Why does Bank Indonesia Govt Set Timeline for Fund matter?
Bank Indonesia Govt Set Timeline for Fund matters because readers are looking for a useful answer, not just a short summary. Good content should match search intent and help them decide what to do next.