Indonesia’s Tax Amnesty Era Closes Permanently Under Purbaya’s Watch
Kabarsaji.com – The Indonesian government has drawn a firm line beneath its two-decade experiment with periodic tax forgiveness. Finance Minister Purbaya Yudhi Sadewa has declared that no further tax amnesty will be introduced during his time in office, effectively ending a cycle of repeated amnesties that began in the mid-2010s. The decision, articulated publicly at a major economics forum in Jakarta, signals a structural shift in how the state intends to approach revenue collection: through disciplined enforcement of existing statutes rather than through episodic blanket pardons.
Legal Exposure as the Core Objection
Purbaya’s primary rationale centers on the vulnerability of tax officials themselves. Under the amnesty framework, taxpayers who participated in prior rounds could still be subjected to audits in later years. When an auditor examines the books of someone who previously declared assets under an amnesty, the resulting scrutiny can drag the official into protracted legal disputes—especially where the underlying data submitted years earlier lacks the granularity needed for a clean audit trail.
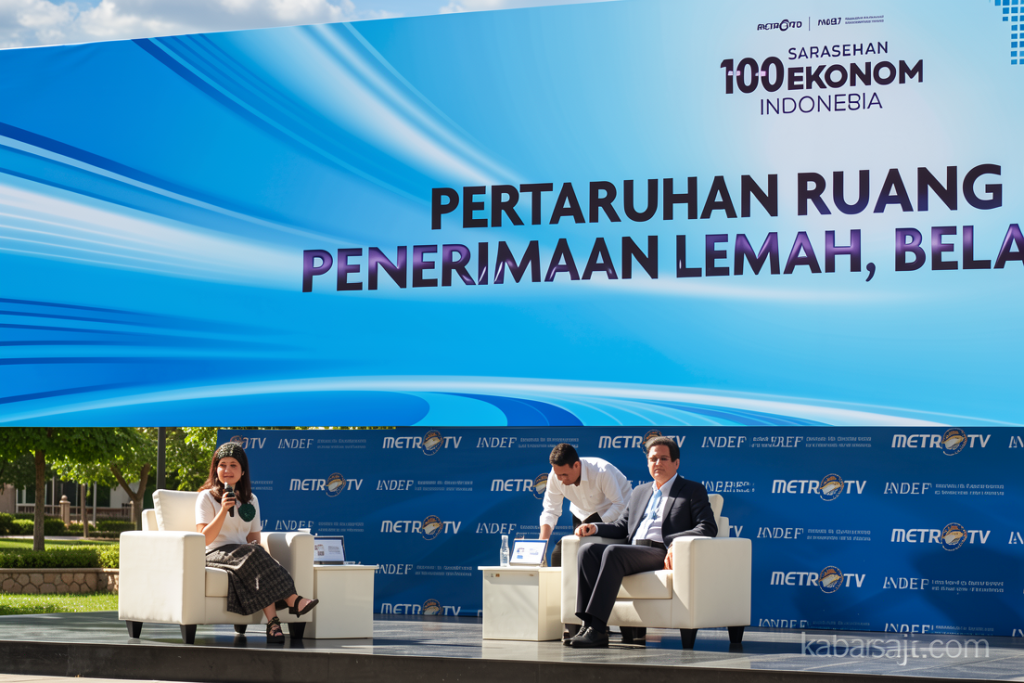
“In my opinion, it is detrimental to taxpayers. A few years later, they can still be audited,” Purbaya told the audience at the 100 Indonesian Economists Seminar 2026, held in Jakarta on Thursday, September 3, 2026.
That ambiguity, he argued, creates a perverse incentive structure. Taxpayers may treat the amnesty as a temporary shelter rather than a genuine reset, knowing that the state retains the right to revisit their filings. For the officials conducting those revisits, the legal exposure is real and ongoing.
A Hard No Through 2027 and Beyond
The minister left no room for ambiguity about the near future. Speaking directly to the question of whether a new amnesty might appear in the 2027 fiscal calendar, he was categorical:
“There is none (no tax amnesty). I have stated that as long as I serve as Finance Minister, there will be no tax amnesty.”
This commitment was not improvised. Purbaya first made the pledge explicit on September 19, 2025, shortly after assuming the finance portfolio. His reasoning at that earlier juncture focused on behavioral economics: repeated amnesties condition taxpayers to defer compliance, operating on the assumption that another forgiveness window will eventually open.
“Repeated amnesties send the wrong message to taxpayers, suggesting they can evade obligations because another amnesty will follow.”
Compliance Over Clemency
With the amnesty option removed from the policy menu, the government’s revenue strategy pivots toward strengthening compliance within the current legal architecture. Purbaya’s position is that state coffers are better filled by ensuring that every taxpayer already subject to existing obligations actually fulfills them, rather than by periodically wiping the slate clean and starting over. The emphasis shifts from retroactive forgiveness to prospective enforcement.
Reassurance for Past Participants
At a separate press briefing held at his office on Monday, May 11, 2026, Purbaya addressed anxieties among business owners and individuals who had declared assets during earlier amnesty rounds. He confirmed that the government would not reopen or reassess those declarations. Assets reported under the Voluntary Disclosure Program or under the original 2016–2017 amnesty will not be subjected to fresh scrutiny.
“In the future, they only need to pay according to their normal business development,” he stated.
The sole exception he identified involves payment commitments that participants agreed to under the amnesty terms but have not yet fulfilled. For all other compliant participants, the matter is closed; no further tax claims will be pursued.
Curbing Institutional Noise
The minister also took aim at what he characterized as unnecessary alarm generated by public statements from the Directorate General of Taxes. Earlier reports had suggested the Tax DG intended to target voluntary disclosure participants who allegedly failed to report every asset. Purbaya said he would reprimand the director general over that announcement.
His broader complaint concerned a pattern of piecemeal tax-related pronouncements—toll-road levies, assorted surcharges, and other measures—announced by mid-level officials without ministerial coordination. To consolidate messaging authority, he declared that going forward, only he would announce tax policy decisions publicly.
“There was talk of toll road taxes, this tax, and that tax. So, in the future, only I will announce tax policies, not the Director General of Taxes, to eliminate confusion,” he stressed.
Background: Two Rounds of Amnesty Under Law 7/2021
Indonesia’s modern tax-amnesty framework traces to Law No. 7/2021 on the Harmonization of Tax Regulations, which provided the statutory basis for both amnesty episodes. The first round operated in 2016–2017, inviting taxpayers to declare previously undisclosed assets in exchange for reduced rates and limited liability. The second round, launched in 2022, took the form of the Voluntary Disclosure Program and functioned as a successor mechanism with its own set of incentives and deadlines. Both programs were designed to widen the tax base by bringing hidden wealth into the formal system.
Purbaya, who previously chaired the Deposit Insurance Corporation (LPS) Board of Commissioners, has treated those two episodes as concluded chapters. His administration’s posture is that the window for retroactive regularization has shut, and that the state’s fiscal agenda now runs exclusively through forward-looking compliance and enforcement.
What This Means for Indonesian Taxpayers
For businesses and individuals still operating outside full compliance, the removal of a future amnesty option raises the effective cost of continued non-declaration. There will be no third round in which previously hidden assets can be surfaced at a discount. The practical implication is that the risk calculus for non-compliant taxpayers tilts decisively toward voluntary regularization under current law before enforcement actions are initiated.
For the broader fiscal picture, the shift underscores a government intent to build revenue capacity on a durable, rules-based foundation rather than on cyclical forgiveness events. Whether that approach can deliver the revenue growth the state requires—without triggering the very compliance gaps it seeks to close—remains the central question for Indonesian fiscal policy in the years ahead.
Related Reading
Frequently Asked Questions
What is Why Finance Minister Purbaya Ends Tax Amnesty?
Why Finance Minister Purbaya Ends Tax Amnesty is the main topic of this guide. The article explains the context, practical details, and next steps readers should understand.
Why does Why Finance Minister Purbaya Ends Tax Amnesty matter?
Why Finance Minister Purbaya Ends Tax Amnesty matters because readers are looking for a useful answer, not just a short summary. Good content should match search intent and help them decide what to do next.